How New York DSCR lenders price judicial foreclosure, prepayment-penalty rules, rent stabilization, Good Cause Eviction, and LLC publication costs in 2026 — Buffalo vs NYC math.
Comprehensive reference: See our New York state guide for rent stabilization, Good Cause, foreclosure, and entity rules. This article focuses on 2026 lender pricing and where deals still pencil.
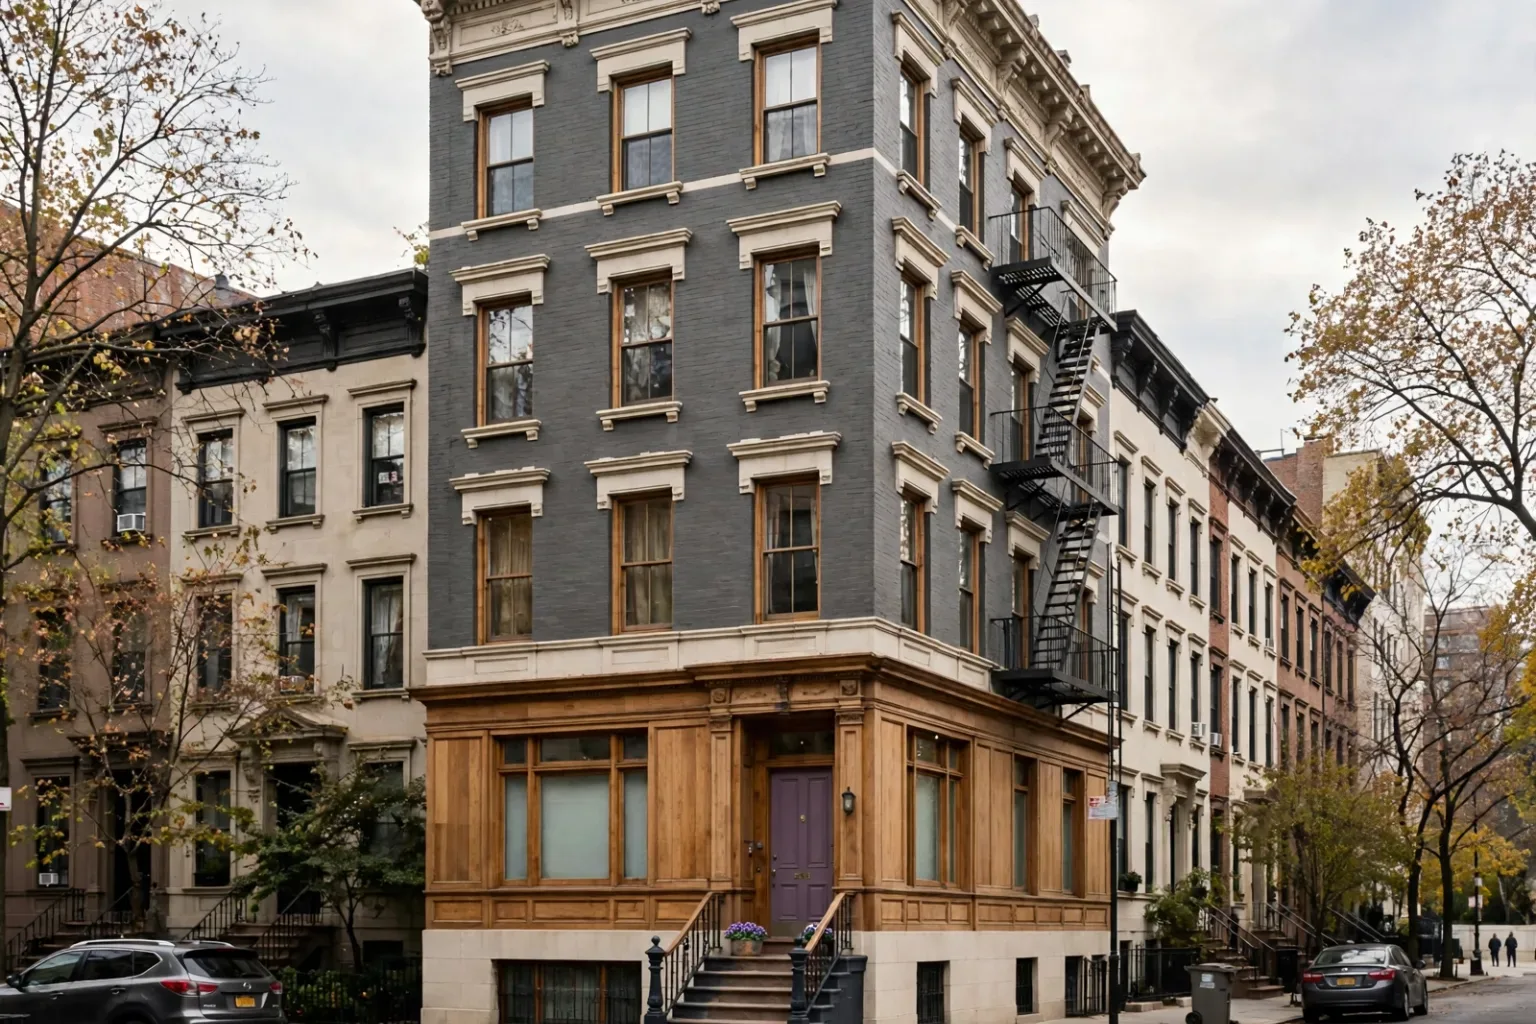
New York is the slowest-collateral state in the country for residential foreclosure — and DSCR pricing reflects it. New York’s prepayment-penalty statute covers owner-occupied homes, so a DSCR loan on a non-owner-occupied rental can still use a step-down PPP — confirm the terms with your lender. Combined with judicial foreclosure and NYC-specific NOI caps, New York DSCR is a specialty market: strong in upstate cash-flow corridors, constrained in stabilized NYC housing stock.
Two New York markets, two DSCR profiles
Upstate (Buffalo, Rochester, Albany, Syracuse): Workforce SFR and small multifamily at $120K–$280K with rents $1,200–$1,800 often produce 1.20+ DSCR at 70%–75% LTV. Good Cause adoption varies by municipality — verify local opt-in status before modeling rent growth. Several lenders maintain active upstate programs.
Downstate (NYC, Long Island, Westchester): Higher prices, lower yields, heavier regulation. Local Law 18 effectively ended whole-unit NYC STR for most investors — underwrite long-term rent only unless you have a compliant registered use case. See STR-restricted cities for NYC specifics.
That decision sits inside our DSCR Authority Blog hub, where DSCR Authority maps program fit and what investors usually prep before booking a strategy call.
That decision sits inside our DSCR Loans by State hub, where DSCR Authority maps program fit and what investors usually prep before booking a strategy call.
That decision sits inside our DSCR Loans by State hub, where DSCR Authority maps program fit and what investors usually prep before booking a strategy call.
That decision sits inside our DSCR Loans by City hub, where DSCR Authority maps program fit and what investors usually prep before booking a strategy call.
That decision sits inside our DSCR Loans by State hub, where DSCR Authority maps program fit and what investors usually prep before booking a strategy call.
That decision sits inside our DSCR Loans by State hub, where DSCR Authority maps program fit and what investors usually prep before booking a strategy call.
What to model before you offer
- PPP structure — Ask each lender for its PPP options and price them against your hold; compare NY quotes to judicial states with similar profiles (New Jersey, Pennsylvania).
- Property tax — Downstate effective rates often exceed 2% of value; upstate is lower but not negligible.
- Entity costs — LLC publication, potential Good Cause rent caps, and rent-stabilization status on 6+ unit buildings.
Portfolio investors
Investors stacking multiple NY properties should use the portfolio DSCR analyzer and confirm whether each lender counts reserves per property or in aggregate — NY files often trigger 9–12 month reserve tiers on lower-LTV no-ratio structures.
Find New York DSCR lenders
Match with lenders that actively fund upstate cash-flow markets and selective downstate suburban deals.